
Q3'26 Warehouse Pricing Index Report

EXECUTIVE SUMMARY
- The National Warehouse Pricing Index decreased 0.5 percent in Q2'26 to 111.7.
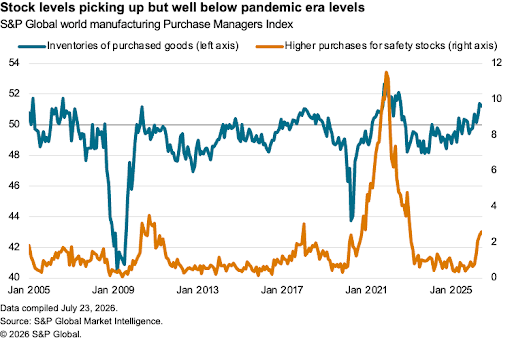
- Stocks of purchased materials hit 51.2 in June, the highest reading since the post-pandemic destocking period in August 2022, as manufacturers rebuild inventory to buffer against ongoing shipping bottlenecks.
- Rising truckload rates are pushing shippers toward LTL and intermodal, and the resulting shift in transit times is forcing warehouses to adjust replenishment and safety stock in response.
The Warehouse Pricing Index (WPI) is available in the Journal of Commerce’s extensive, multi-channel dashboard, Gateway. Learn more about Gateway and how WarehouseQuote helps logistics managers make informed supply chain decisions.
Key Enablers are Surfacing
For much of the past year, the U.S. supply chain has operated in a kind of holding pattern. Import volumes softened as front-loaded inventory worked its way through the system, warehouse pricing plateaued as speculative big-box supply from 2021-2023 slowly absorbed, and operators leaned on caution rather than commitment. That strategic pause is starting to show real cracks. Not because any single indicator broke out, but because several long-static signals are all moving in the same direction at once.
Industrial vacancy fell to 6.9% in the second quarter, the lowest reading in over a year, with absorption climbing to its strongest first-half pace since 2023. Warehousing employment has grown for four consecutive months, and wages in the sector have kept pace: evidence that labor and space are tightening together, rather than one propping up the other. Prologis, the industry's largest logistics landlord, raised full-year guidance for the second time this year on the back of record leasing volume. None of this amounts to a new boom, but after several quarters of waiting for a clear signal, operators finally have one worth acting on. The businesses that treat this as the moment to commit to network decisions will be better positioned than those still waiting for more certainty that may not come before the opportunity does.
U.S. Warehouse Market Watch
- 6.9% National Industrial Vacancy Rate (-0.1 percent)
- 111.7 National Warehouse Pricing Index Reading (-0.5 percent)
The Midwest Holds the Line
The Midwest remains the tightest region for warehousing pricing in the country, climbing another 0.2% this quarter to 128.6 and extending its lead over every other region. It never carried the big-box overbuild that weighed down the coasts, and that discipline continues to show up in pricing power the other regions are still working to recover.
The Coasts Diverge
The two coastal regions split directions this quarter. The Northeast has stabilized after bottoming out in April, edging up slightly through May and June. The West kept falling, closing the quarter at 104.8, back to the same level it sat at exactly one year ago. Any read on the coast "catching up" to the interior needs to wait until the West breaks out of that holding pattern.
The National Index Extends Its Slide
The National WPI slipped again in Q2, down 0.5% to 111.7, the third straight quarterly decline. Midwest strength continues to offset a soft West and a South holding roughly flat.
Time is the Ultimate Bottleneck For Logistics
Contributor: Chris Rogers, Head of Supply Chain Research, S&P Global Market Intelligence
The Strait of Hormuz. Bab al Mandab. The Suez Canal. The Panama Canal. The Strait of Malacca. The Taiwan Strait. In 2026, the names of the key maritime bottlenecks have gone from being a theoretical matter to bringing real world challenges for shippers and logistics operations.
They will continue to bring challenges in 2027. The US – Iran conflict shows few signs of being resolved and S&P Global analysis shows supply chains, particularly in petrochemicals, may not fully recover until the first quarter of 2027 even if the Strait of Hormuz is opened shortly.
The Panama Canal is entering the latest El Nino with pre-emptive capacity reductions as the Authority aims to preserve water in the Gatun Lake. In previous El Niño events shippers have dealt with reduced Panama Canal access by shipping to the US west coast instead of the east and moving onward by rail. In May 2015 to April 2016 shipments to the US west coast accounted for 67.2% of total US seaborne imports of containerized freight versus 62.5% in the subsequent seven years. In 2023/2024, the percentage was actually lower at 57.9% but was more volatile during the period than normal, reflecting a mixture of labor strike risks on each coast as well as disruptions to Red Sea shipping from October 2023 onward.
However, at S&P Global we always say that “logistics finds a way”. Rerouting, alternative sourcing locations, adapting production techniques and careful logistics staging can ensure goods continue to flow for several months after an initial shock occurs.
As we head into the peak delivery season, however, we are reminded that time is the bottleneck that can only be mitigated with careful planning and agile inventory management
Part of the seasonality in total trade is driven by the airfreight shipping of new smartphone, computer and videogame electronics releases historically peaking in October 2026, though firms are starting to spread their product releases through the year.
For maritime volumes, a bigger driver is seasonal demand for leisure goods (including toys), winter apparel and large-scale consumer electronics such as televisions. S&P Global data shows there has been early shipping of those goods as firms seek to preempt higher tariffs. We expect continued trade policy uncertainty in 2027, particularly in connection to USMCA as well as regarding tariffs where the Trump administration is set to continue to use a mixture of new investigations of different products and countries and adaptations of existing duties to encourage reshoring and provide leverage in trade negotiations.
Firms can deal with time and other bottlenecks in part by building precautionary inventories. However, that comes with additional cash costs that are rarely welcome in publicly traded companies’ balance sheets.
While manufacturers on average experience less seasonality than retailers, there is little evidence that long-term inventory strategies have changed, even though there is evidence of increased safety stocks.
Stocks of purchased materials held have picked up recently according to the S&P Global World Manufacturing PMITM, reaching 51.2 in June (over 50 indicates expansion) from 49.7 in January, marking the highest level since the post-pandemic destocking period in August 2022. Similarly, the buildup of safety stocks has also increased, though only to the level seen in January 2023 and around one-fifth the rate of their post-pandemic peak in December 2021.
Time is the ultimate bottleneck which cash for inventories can start to unblock. The willingness to spend among finance departments may not be there, yet.
Every Freight Decision Becomes an Inventory Decision
Contributor: Mathew Leo, Director of Research & Market Intelligence, C.H. Robinson
Tightening truckload capacity has pushed transportation costs higher, with Q3 dry van spot linehaul rates expected to be up approximately 45% y/y, resulting in many shippers re-evaluating how freight moves through their networks. While truckload remains the preferred option for many shipments, rising costs have encouraged some companies to shift suitable freight into the LTL space or move via intermodal. While this may be necessary to save on the high freight rates, there remains some effects that may show up downstream in the supply chain.
Namely, when transit times shift, inventory planning changes. For example, a truckload shipment from Chicago to Houston takes two days when moving on a full truckload. In that same lane, it may take 3 days moving via LTL and approximately 4 days moving via intermodal. These transit times will vary depending on lane and shipment characteristics. There isn’t one option that is inherently better or worse, but each comes with different tradeoffs. As shifts between these modes become more prevalent, supply chain managers and warehouse operators may find themselves adjusting replenishment schedules, labor planning, and inventory strategies to accommodate the change.
For retailers, manufacturers, and distributors, the challenge often comes down to balancing transportation expenses against inventory carrying costs. Faster transportation can reduce the amount of inventory required across the network. Slower transportation may lower freight spend but increase the need for safety stock. The warehouse frequently sits at the center of that decision.
Seasonal demand patterns add another layer to the equation, from both the transportation and warehousing lens. Back-to-school season is currently consuming much of the inventory that retailers spent months building. Distribution centers and warehouses have already done much of the heavy lifting. The majority of linehaul transportation has been completed, with mostly just local delivery for online orders still occurring. Products are moving from storage locations to store shelves and ultimately to consumers. As peak back-to-school demand passes, some warehouse space tied to those seasonal products will begin to free up, reducing storage requirements in those associated industries.
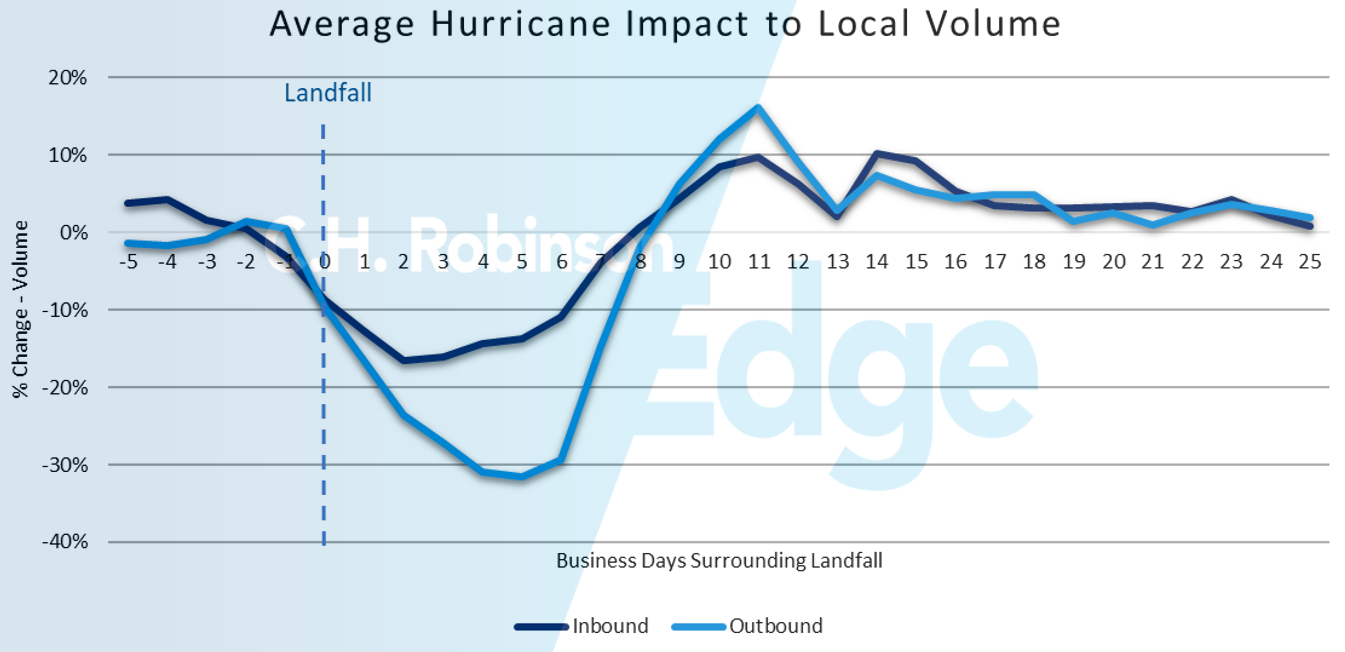
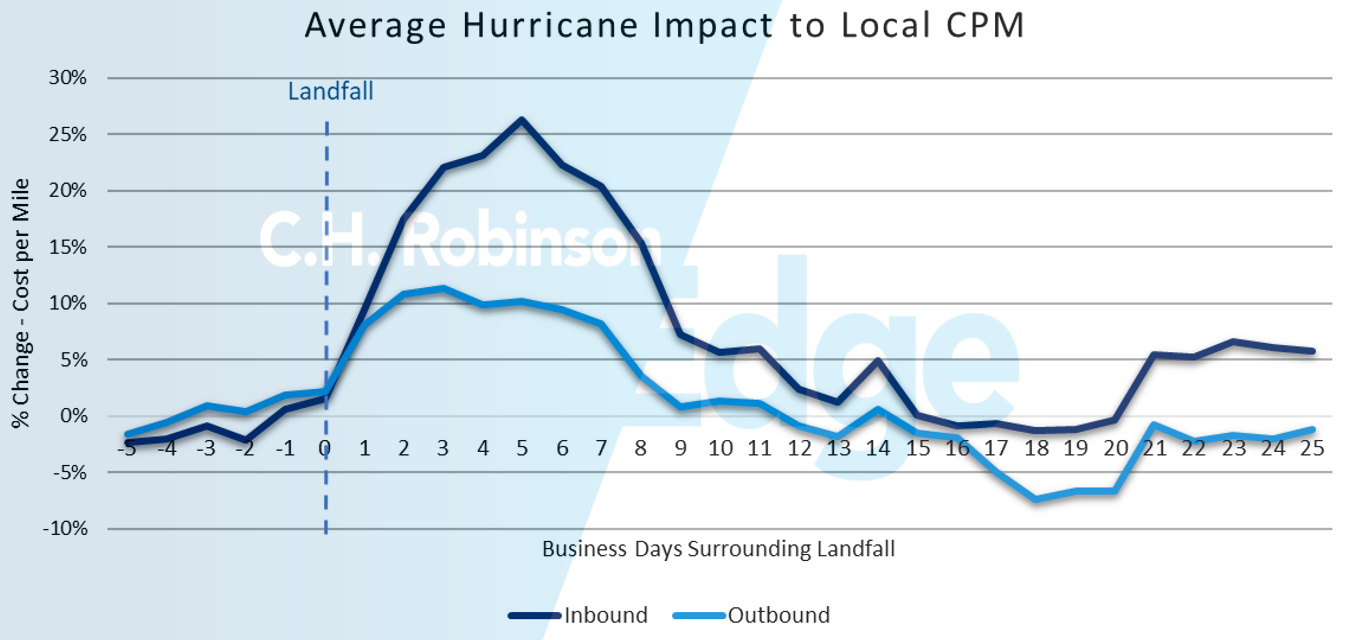
At the same time, attention is shifting toward hurricane season. Unlike back-to-school inventory, which follows a relatively predictable calendar, hurricane-related demand can emerge quickly and create significant regional swings in both transportation and warehousing. Emergency supplies, bottled water, generators, pumps, building materials, and other storm-related products are often positioned near higher-risk areas long before a storm makes landfall. In the days immediately after landfall, much of the freight that actually moves into these affected areas is only this relief freight from these staging areas. It takes on average two weeks after landfall before these locations see volumes surge beyond the pre-storm baseline, and a few weeks after that before returning to normal.
Transportation networks often prioritize affected regions during these periods, pulling capacity toward areas with urgent demand and increasing costs in the process. Those transportation shifts can influence inventory movement far beyond the immediate disaster zone.
There are several other factors currently influencing the ebbs and flows of freight such as trade policy changes and the volatile fuel market which add to the complexity, but the common thread remains inventory positioning. Whether organizations are preparing for tariff impacts, responding to changing transportation costs, or managing seasonal demand cycles, many are evaluating where inventory should be held and how quickly it can be replenished. Those decisions directly influence warehouse utilization.
The warehouse has increasingly become the supply chain's shock absorber. When transportation costs rise, freight moves differently. When storms disrupt networks, inventory is repositioned. When seasonal demand shifts, product flows adjust. In almost every case, warehouses, distribution centers, manufacturing facilities, and retail networks are asked to absorb the impact.
The most successful companies are the ones that build flexibility into transportation network design and inventory planning. Freight markets are expected to experience significant changes to finish this year and into 2027, creating downstream impacts on warehousing. Those best equipped to handle the fallout will be the ones that view inventory strategy and transportation strategy as part of the same conversation rather than two separate functions.
Explanation of Terms
Industrial Real Estate Vacancy Rates
Industrial real estate vacancy rate is the percentage of available industrial property, such as a warehouse or distribution center.
United States Regional Divisions
Midwest
- East North Central: Illinois, Indiana, Michigan, Ohio, and Wisconsin
- West North Central: Iowa, Kansas, Minnesota, Missouri, Nebraska, North Dakota, and South Dakota
Northeast
- New England: Connecticut, Maine, Massachusetts, New Hampshire, Rhode Island, and Vermont
- Middle Atlantic: New Jersey, New York, Pennsylvania
South
- South Atlantic: Delaware, Florida, Georgia, Maryland, North Carolina, South Carolina, Virginia, Washington DC, and West Virginia
- East South Central: Alabama, Kentucky, Mississippi, and Tennessee
- West South Central: Arkansas, Louisiana, Oklahoma, and Texas
WarehouseQuote’s Economic Commentary Disclaimer
The material and content used in this publication is for informational purposes only. Reference to any third party (including external hyperlinks) does not constitute or imply the endorsement of said third party. WarehouseQuote does not warrant the accuracy or completeness of the Content. The views and opinions expressed herein are those of the author and do not necessarily reflect the official policy or position of WarehouseQuote. Reproduction of the Content may be made only with the written permission from WarehouseQuote.
Sources
About WarehouseQuote
WarehouseQuote is a managed warehouse and fulfillment solution. Through operational expertise, purpose-built technology solutions, and an extensive warehouse and fulfillment network, we help businesses optimize their warehouse and fulfillment operations.
